Structural demand
DoW modernization, Replicator, the Joint Warfighting Concept, FMS expansion, and contested logistics create multi-decade demand for U.S.-sourced attritable mass and precision munitions.
 Defense Sector
A Wyoming-domiciled, U.S. citizen-owned four-vertical defense manufacturer — precision ammunition, attritable swarm UAS, high-margin training and sustainment, and high-rate launch — held as a portfolio investment of Definitely Green.
Stamus Quattuor — Defendimus Una · We Stand as Four — We Defend as One
Saber Defense is an American Tier-One platform purpose-built for attritable mass and precision munitions. Ammunition is the near-term cash engine. Helix Swarm™ is the high-growth autonomy franchise. Support & Command is the high-margin services layer. Catapult is the launch enabler. Together they close a kill-chain that no single-point competitor can replicate — and ammunition free cash flow finances a material share of the scale-up.
DoW modernization, Replicator, the Joint Warfighting Concept, FMS expansion, and contested logistics create multi-decade demand for U.S.-sourced attritable mass and precision munitions.
Owned manufacturing, a $745M Helix IP estate, and ammunition free cash flow that internally funds $250M+ of Helix and Catapult ramp reduce external capital intensity and de-risk scale-up.
Catapult high-rate launch, Helix attritable swarm, Support & Command Digital Twin training and CLS, plus ammunition logistics form a closed-loop capability no pure-play competitor matches.
Four operating companies under a single Wyoming parent, 50/50 parent–founder ownership at each subsidiary, and a Master Management & Services Agreement that consolidates capital, IP, and governance.
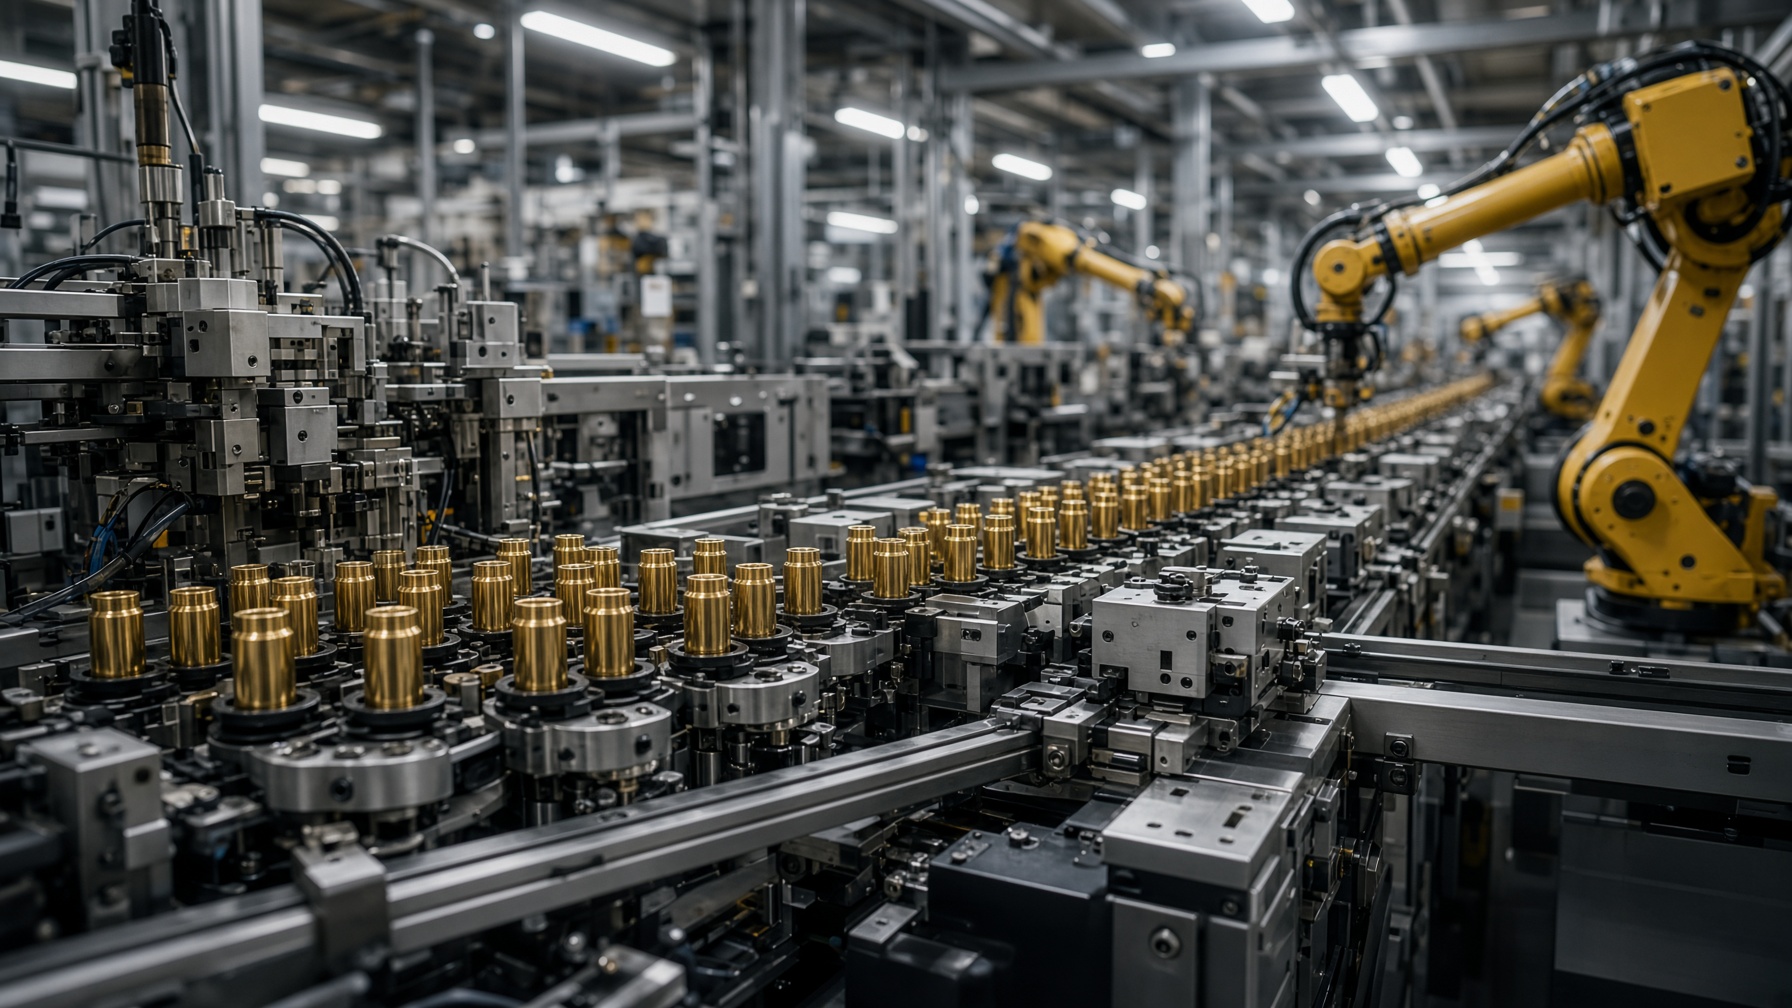
Precision small-arms, large-caliber, and shotgun ammunition with a path to full vertical integration of primers, casings, projectiles, and propellant. Target capacity exceeds 500 million rounds per year across 27 loaders, with ATF Type 06, ITAR registration, and Berry Amendment / DFARS domestic preference.
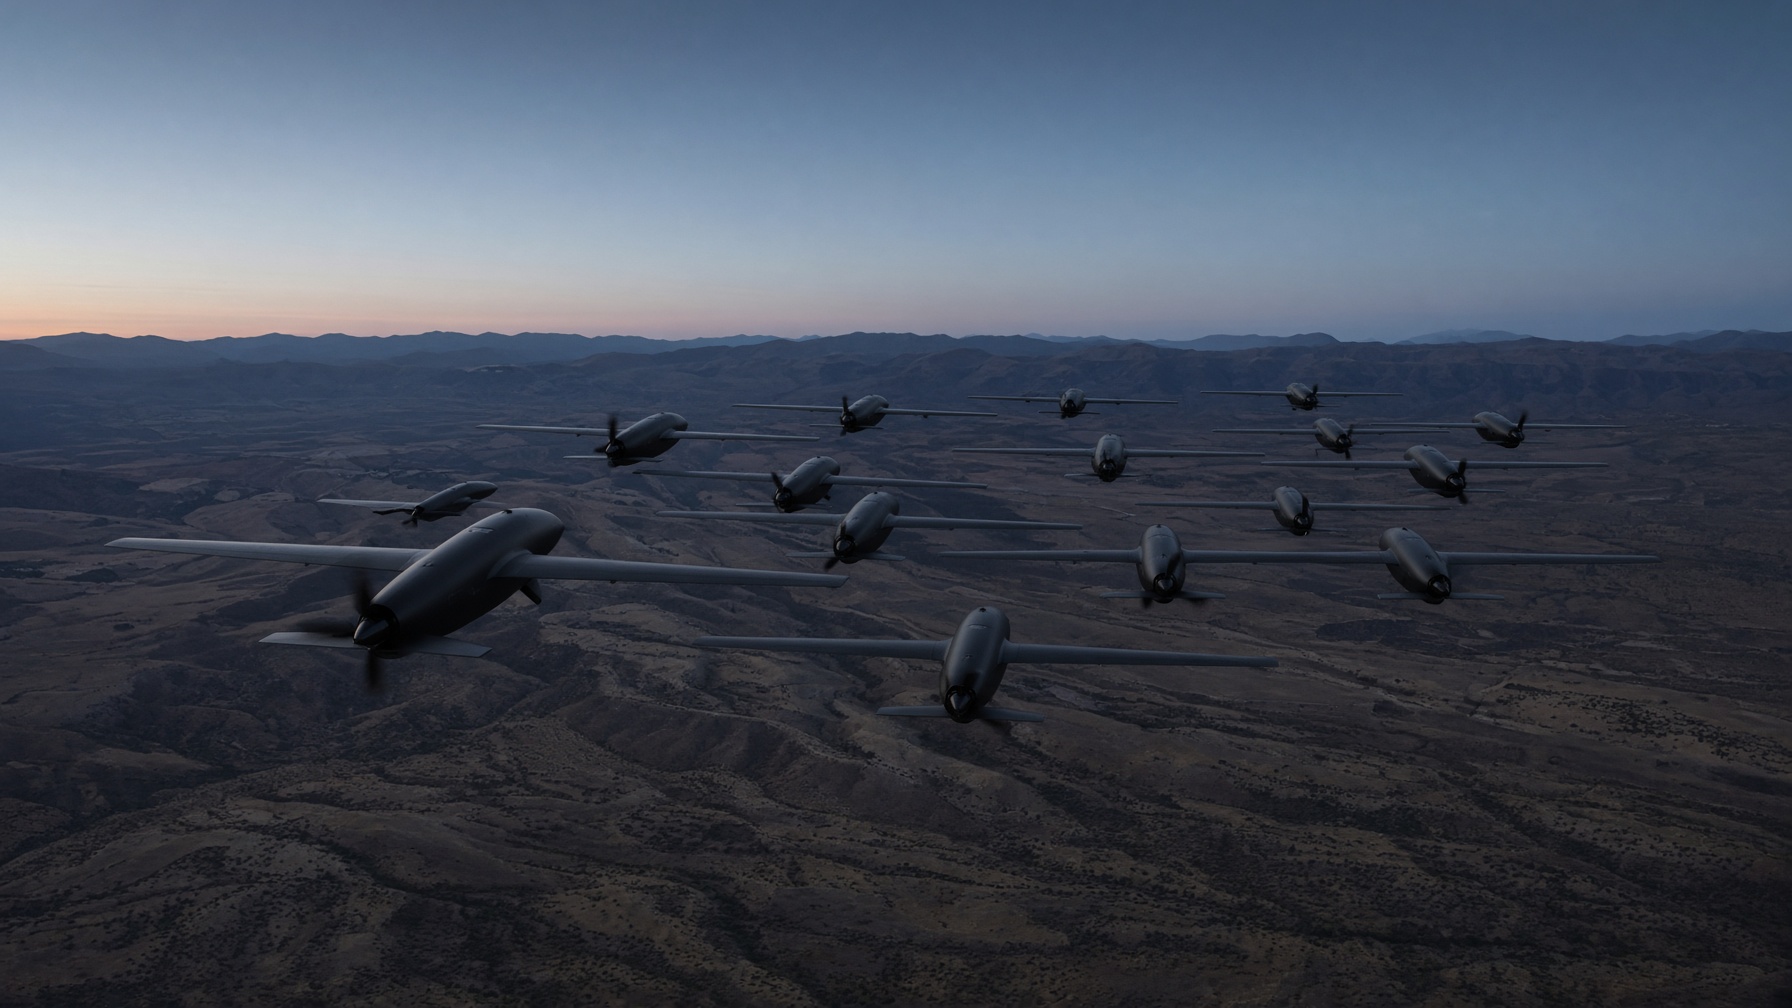
A 5 kg-class fixed-wing attritable UAS built for mass: titanium-carbon EMP-hardened exoskeleton, AeroHydroCell™ hybrid power, MARL-LAC hierarchical autonomy with a neuromorphic ASIC, and a hot-swap five-cartridge payload bay (kinetic, thermal, EMP, aqua, ISR, decoy). Target rate is 120,000 units per year at a ~$152k blended ASP.
Training and certification, contractor logistics support, Digital Twin mission rehearsal and after-action review, reachback C2, and FMS curriculum packages. Capital-light services that scale with fielded Helix inventory on the same SHAOS digital thread that runs production and swarm operations.
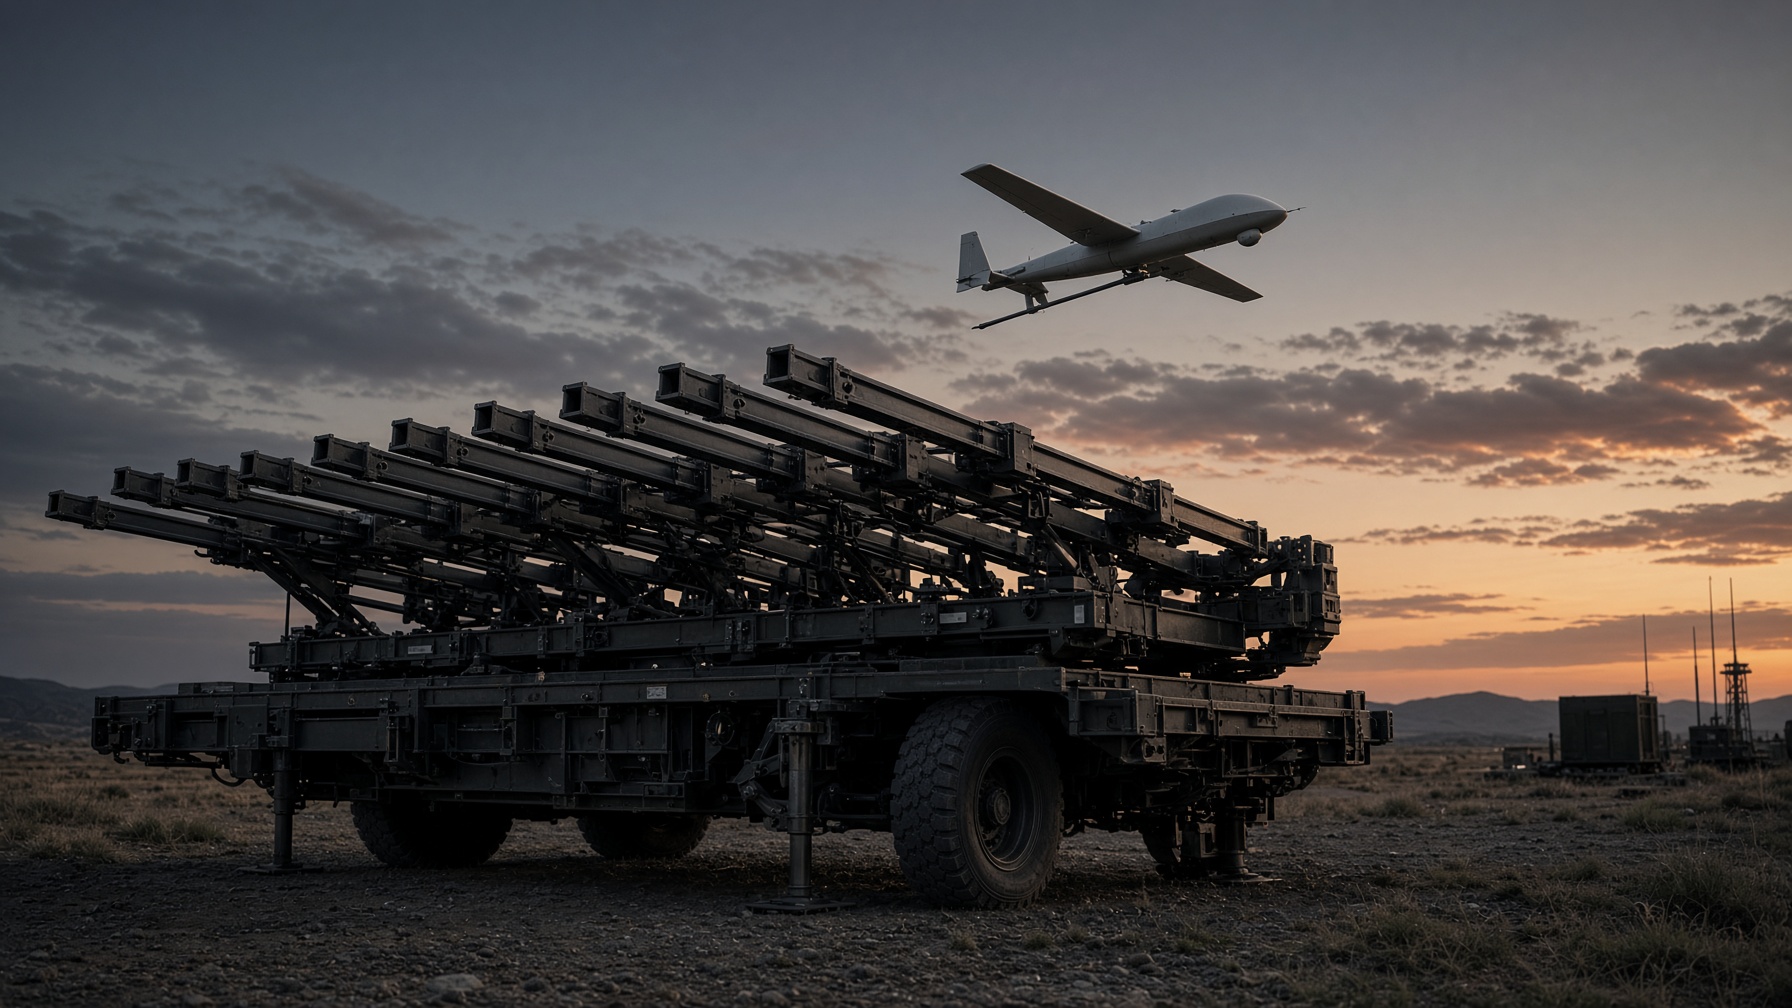
Multiple Parallel Pneumatic Catapult batteries (baseline 12-rail, ASP $3.69M) delivering 25–40+ drones per minute while fully preserving Helix EMP hardening. Canister magazine end-loading, hot-swap interface, and truck, trailer, or 40-ft container mobility for distributed, no-runway operations.
Ammunition free cash flow is allocated at Parent to Helix production ramp and Catapult tooling — lowering net external capital required versus the headline raise.
~$680–720M
Cumulative Y1–Y5. Dividend / intercompany loan to Parent for Helix and Catapult capex.
~$250M+
Self-funding reduces external dependency. Series A is sized for acceleration, campus, IP, compliance, and reserve.
$12.21B
Cash conversion turns positive in Y3. Equity-only Series A; optional 8% equipment notes for ammo machines only.
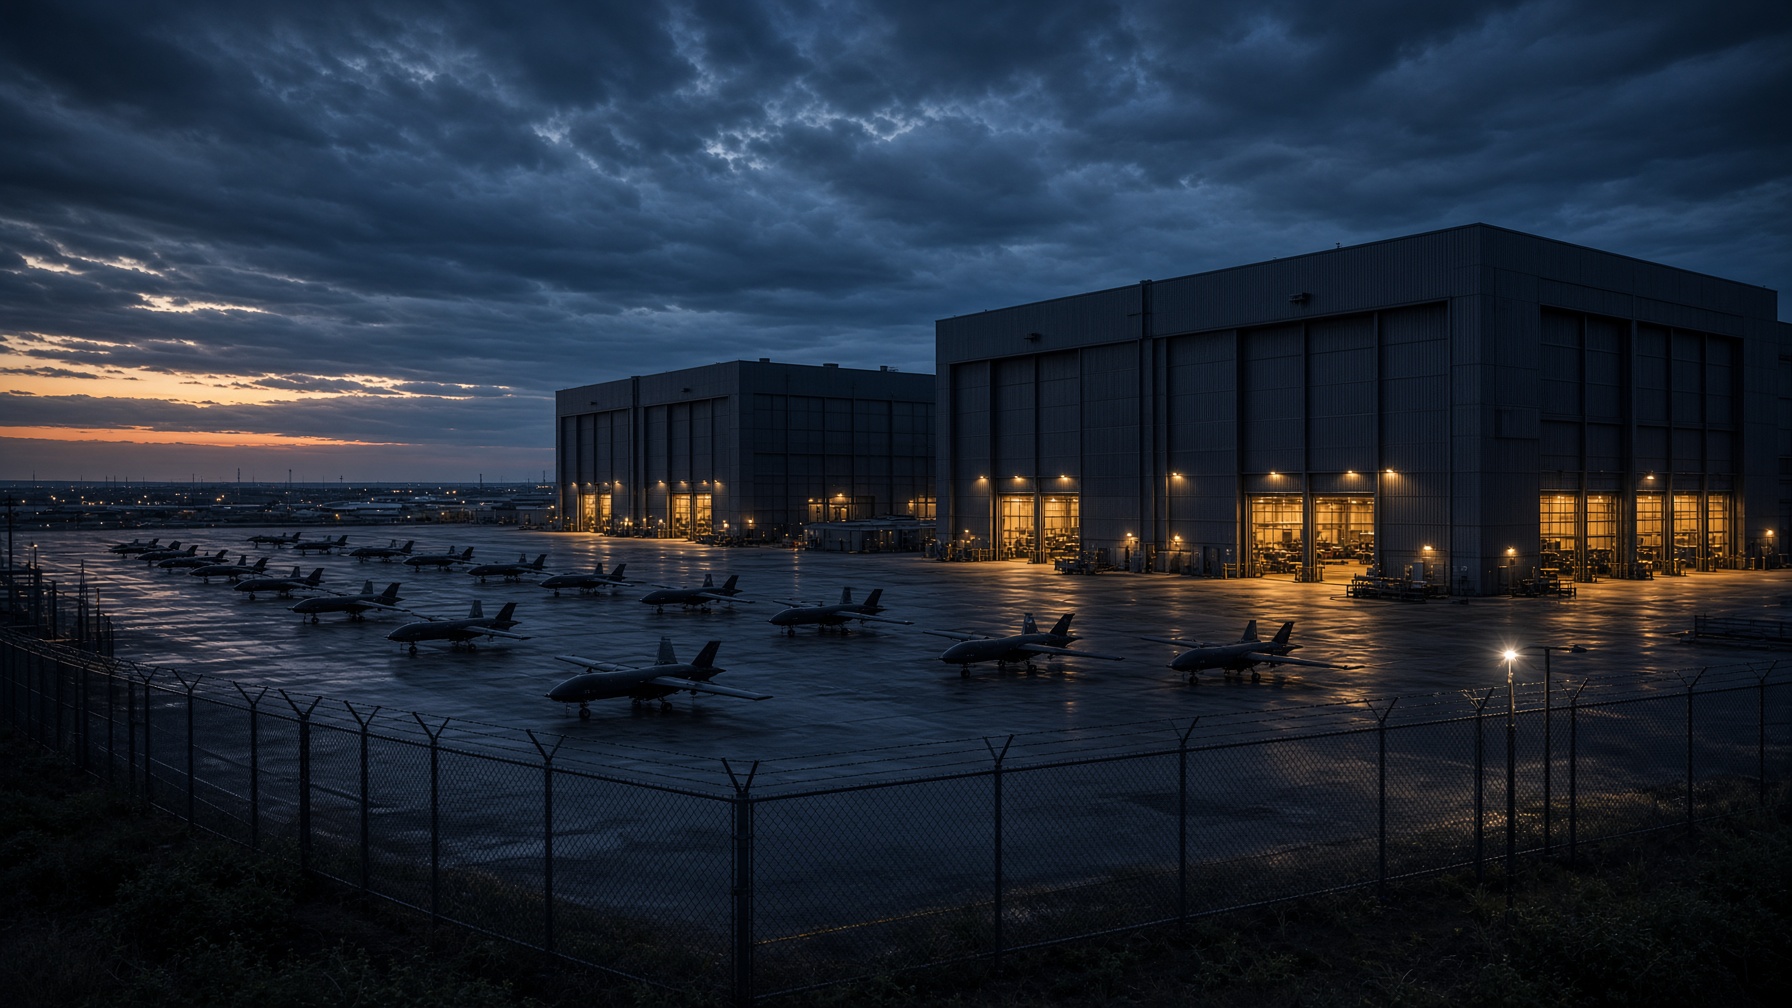
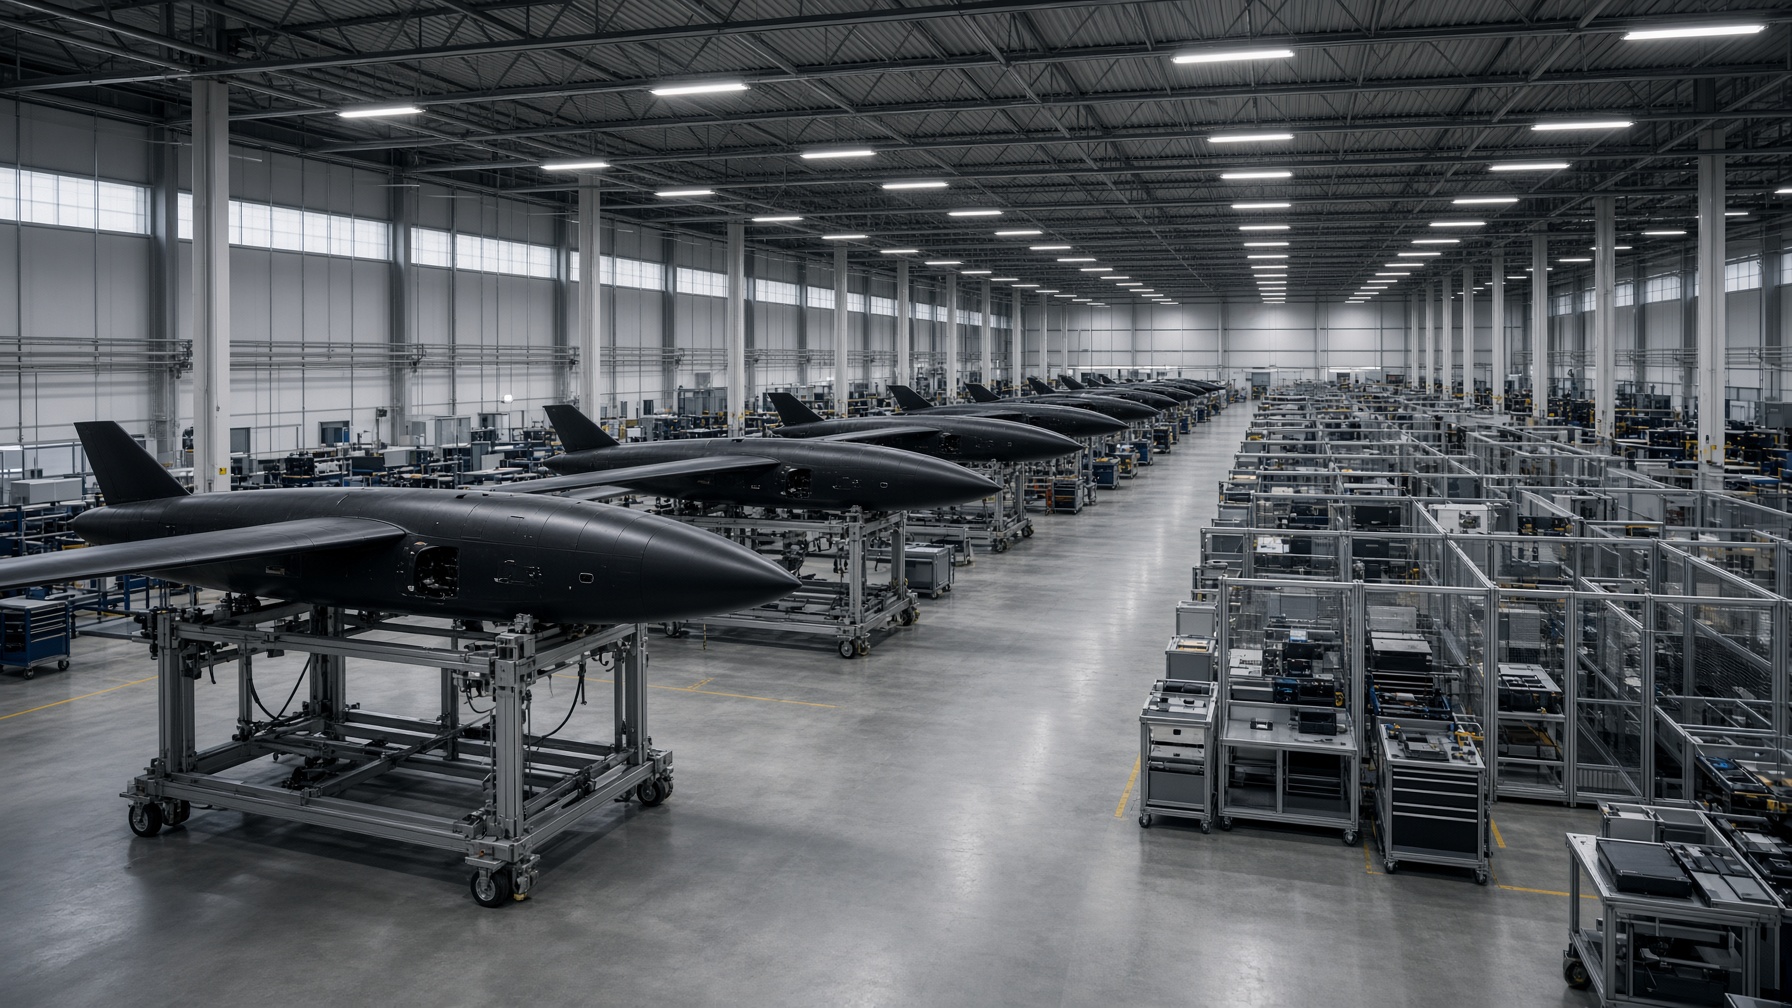
838-acre HUBZone sovereign campus · 150k+ SF production
Primers, cases, and powder path. 500M+ rounds/year. ATF Type 06. DPA Title I/III ready.
311k SF · 36' clear · cross-dock · ESFR
Airframe, electronics, final assembly, payload, test, 120k units/year, Digital Twin training, CLS, and reachback.
210,653 SF · 36' clear · front-load · ESFR
Heavy fabrication, rail assembly, pneumatics, integration, and test.
Consolidated planning estimates from the July 2026 institutional business plan. Figures in millions of dollars. Actual results will vary.
Stacked mix with total revenue line · figures in millions
| Metric ($M) | Y1 | Y3 | Y5 | Y7 |
|---|---|---|---|---|
| Revenue | 590 | 4,100 | 11,450 | 20,640 |
| Gross Margin | 37.0% | 45.0% | 48.0% | 49.5% |
| EBITDA | (62) | 902 | 3,550 | 7,162 |
| EBITDA Margin | n/m | 22.0% | 31.0% | 34.7% |
| Net Income | (74) | 690 | 2,761 | 5,581 |
| Net Margin | n/m | 16.8% | 24.1% | 27.0% |
| Free Cash Flow | (216) | 376 | 2,260 | 5,042 |
| Cumulative FCF | (216) | 60 | 3,482 | 12,208 |
Consolidated platform. Y1–Y2 are ramp years; steady-state ratios emerge Y5–Y7. Equity-only capital structure.
| Ratio | Y3 | Y5 | Y7 | Benchmark | Assessment |
|---|---|---|---|---|---|
| Current Ratio | 4.95x | 8.52x | 12.99x | > 1.5x | Fortress liquidity |
| Quick Ratio | 3.78x | 7.35x | 11.82x | > 1.0x | Very strong |
| Debt-to-Equity | 0.00x | 0.00x | 0.00x | < 1.0x | Debt-free |
| Gross Margin | 45.0% | 48.0% | 49.5% | > 35% | Strong |
| EBITDA Margin | 22.0% | 31.0% | 34.7% | > 20% | Excellent |
| Net Profit Margin | 16.8% | 24.1% | 27.0% | > 10% | Very strong |
| Return on Equity | 50.9% | 48.2% | 35.9% | > 15% | Excellent |
| FCF Margin | 9.2% | 19.7% | 24.4% | > 10% | Strong self-funding |
| Cash Conversion (FCF/EBITDA) | 41.7% | 63.7% | 70.4% | > 50% | High-quality earnings |
| Net Debt / EBITDA | −0.60x | −1.12x | −1.77x | < 2.0x | Net cash |
| Cumulative FCF ($M) | 60 | 3,482 | 12,208 | — | Positive by Y3 |
Headline terms, capture channels, leadership, compliance posture, and phase gates drawn from the master four-vertical business plan.
Definitely Green holds Saber Defense as a defense-sector portfolio company. Review the operating platform, or contact us to discuss the investment.
Summary prepared from the Saber Defense Corp Master Institutional Four-Vertical Business Plan (July 2026, v5). Planning estimates only. Contains summaries of ITAR-controlled technical data. Not an offer to sell securities. Independent diligence required.